01
START WITH YOUR STORYApply online
Tell us about your business sales, the amount you want to request, and what you have in mind. Our guided application keeps the first step simple.
An MCA is generally structured as an advance in exchange for an agreed amount of future business receivables. Explore what that means for your business—before making a commitment.
A merchant cash advance generally provides an upfront amount in exchange for the purchase of a specified amount of future business receivables.
The written agreement sets the purchased amount, collection method, reconciliation provisions, and other obligations. The agreement and applicable law determine how the arrangement is treated.
Applying starts a conversation. Understanding the terms helps you decide what comes next.
Tell us about your business sales, the amount you want to request, and what you have in mind. Our guided application keeps the first step simple.
Your business profile, revenue, time in business, and existing obligations provide context for review. Additional verification or documentation may be requested.
If an offer is available, review the advance, purchased amount, fees, remittance schedule, and reconciliation terms. Ask questions before accepting.
The potential value of an MCA depends on your purpose, your operating cash flow, and the actual terms.
Your revenue and business activity help inform the review—not just the size of your ambition.
Use MCA proceeds for eligible business needs, from inventory and payroll to your next busy season.
One guided online application. No account to create. No SSNs or banking credentials requested here.
Understand the collection schedule, revenue adjustments, and total purchased amount before agreeing.
Share your goals and questions so the next conversation starts with your actual business needs.
From everyday operations to a new opportunity, start with the business need—not just the advance amount.
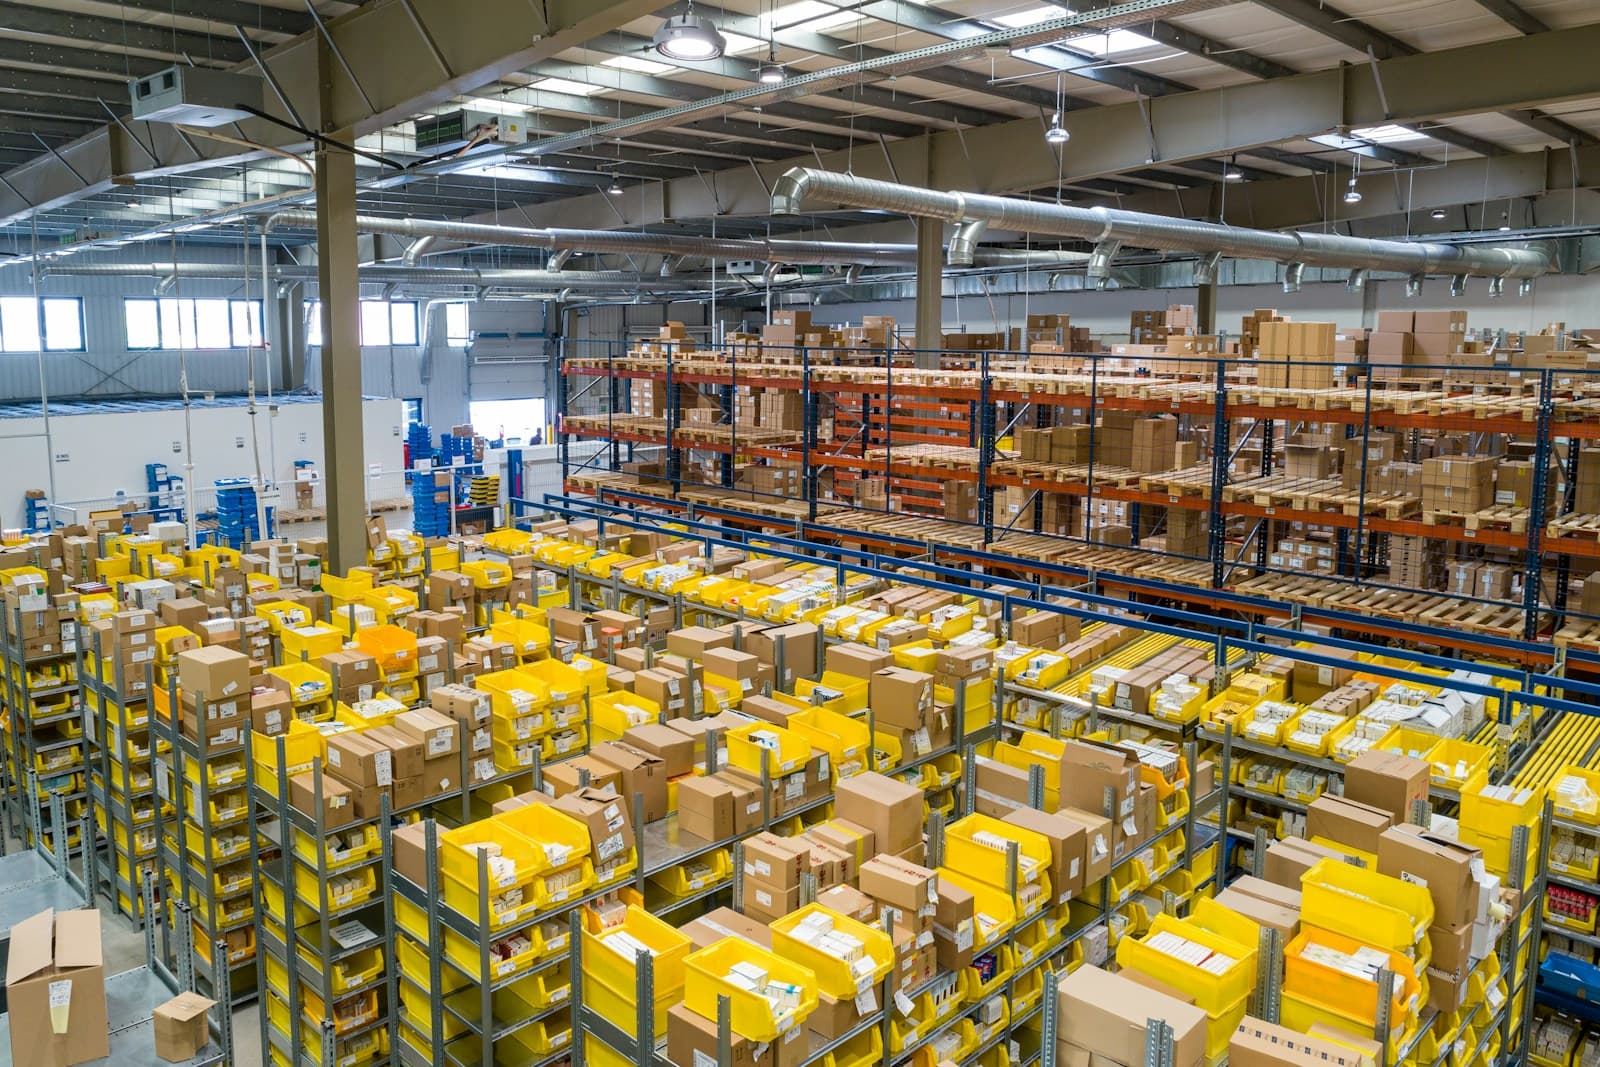
Prepare inventory for customer demand and supplier lead times.
Plan for payroll, suppliers, and the timing between expenses and incoming sales.
Consider upgrades, new capacity, and the practical costs of your next phase.
These are potential uses of MCA proceeds, not separate funding products. Permitted uses and availability depend on the agreement and review.
Eligibility is assessed individually. We don’t publish guaranteed approvals, minimum revenue thresholds, or funding timelines.
An MCA is generally a purchase of future business receivables. It deserves a clear-eyed look at both the opportunity and the obligations.
Read important disclosuresYou receive an advance in exchange for an agreed amount of future business receivables. The agreement defines what is purchased and your obligations.
A factor rate may multiply the advance to calculate the purchased amount. It is not an APR. Ask about all fees, net proceeds, total dollar cost, and applicable annualized disclosures.
Collections may use a share of sales or scheduled debits. Confirm frequency, how changes in revenue are handled, and how to request reconciliation.
Frequent collections can strain operating cash flow. Review guarantees, security interests, default provisions, and restrictions on additional funding.
This is a general comparison. Actual terms and applicable law control. Super MCA focuses on MCA inquiries.
| What to compare | Merchant cash advance | Traditional business loan |
|---|---|---|
| General structure | Purchase of future business receivables | Borrowing principal under a loan agreement |
| How cost is described | Purchased amount, possible factor rate, and fees | Interest rate, fees, and applicable APR disclosures |
| Collection arrangements | Sales-based remittances or scheduled debits; review reconciliation terms | Payments according to the loan’s repayment schedule |
| Questions worth asking | What if sales decline? What is the total purchased amount? | How is interest calculated? What are the term and payment obligations? |
Both arrangements may carry significant costs, guarantees, and security interests. Neither is automatically suitable for every business.
Estimate stock requirements, supplier lead times, and your expected sales cycle. Consider whether frequent remittances leave enough room for reorder costs.
Identify the gap you want to address and its cause. Budget for payroll, supplier obligations, and collections from the MCA before accepting an agreement.
Outline project costs, setup time, and when improvements may generate revenue. MCA proceeds may be used for eligible upgrades; this is not a separate equipment financing product.
A few things worth understanding
before your next business decision.
A merchant cash advance is generally structured as an upfront purchase of a specified amount of future business receivables. It is different from a conventional business loan. The actual agreement and applicable law determine the arrangement and your obligations.
A factor rate is a multiplier that may be used to calculate a purchased amount from the advance amount. It is not an annual interest rate or APR. It does not, by itself, describe all fees or the effect of how quickly collections occur. Ask for the total cost and applicable annualized disclosures.
Depending on the agreement, collections may be taken through a share of card sales or scheduled bank debits, often daily or weekly. Understand whether collections adjust to actual revenue, how reconciliation is requested, and what happens when sales decline.
Review may consider business revenue and deposits, time in business, industry, location, existing obligations, and verification information. Criteria and availability vary. There are no guaranteed approvals or published minimums on this website.
Ask about the total purchased amount, fees, frequency of collections, reconciliation rights, guarantees, security interests, and restrictions on other funding. Frequent collections can put pressure on operating cash flow. A factor rate is not an APR, and early delivery of receivables may not reduce the purchased amount.
Start your merchant cash advance inquiry. Get clear on the possibilities before you decide.